Piedra Insurance Concepts
  • Home
  • About Us
  • Solutions
    • Group Health/Wellness
    • Individual Health
    • Long Term Care
    • Life Insurance
    • Annuity
  • Contact Us

What is Life Insurance?

Incorporating life insurance in to your long-term plan helps provide peace of mind for those who depend on you. The primary benefit of life-insurance is what the industry calls a "death benefit" or a "face value" of which is guaranteed non-income taxable payment to your beneficiary (wife, children, business partner, etc.) at time of the policy holder's passing. 


Life insurance has evolved over the years to serve more than just to provide a face value. Many living benefits are also supplied of which aim to establish a life insurance policy as a tangible asset that accumulates value of which can be utilized during the life of the policy. 


There are many different types of life insurance policies with almost endless number of options and additional benefits that can be elected. Piedra Insurance Concepts is here to guide you through the advantages and type of policies that will work for you. 
Young green plant sapling growing on a branch.

Types of Life Insurance

Term Life

Whole Life

Whole Life

This is your basic and most economical type of life insurance design to provide temporary or "term" based coverage, spanning from 10-30 year terms.


These policies provide death benefit to the beneficiary upon the policy holder's death only during the term of which the policy is active. Death benefits are considered non-taxable income to the beneficiary. 


Term life insurance policies do not contain a cash value of which the remaining types of life insurance policies do. 

Whole Life

Whole Life

Whole Life

Typically what most attribute life insurance to. A whole life policy is designed to remain active and provide coverage for the entirety of the policy holder's life. Premiums are level set and remain stagnant throughout the life of the policy. 


Additionally, whole life insurance includes a cash value of which is a separate funded account that is included with your premium. This fund is invested in the insurer's conservative general investment account of which provides GUARENTEED tax-deferred gains/accumulation. 


Depending on the type of policy selected and/or and riders selected, additional living benefits are offered such as accelerated benefits which allows the policy holder to pull from the death benefit/face value of the policy in the event of disability or in some cases long-term care needs. 

Universal Life

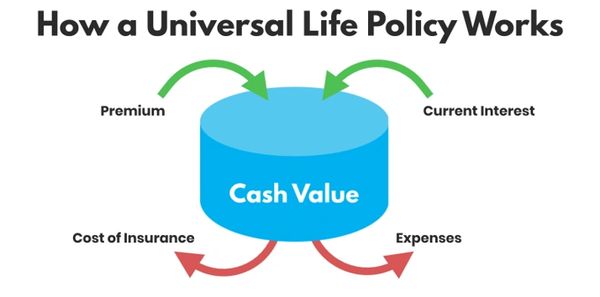
A Universal Life Policy is designed to provide coverage throughout the policy holder's lifetime and provides the same type of living benefits.


Unlike a traditional whole life policy, Universal life insurance offers flexible cash value based premiums. The policy holder pays premiums that immediately fund the cash value account of which generates interest in the insurance company's general account of which is used to fund the Cost of Insurance (protection - Death Benefit Fund) and Insurer's expenses (Admin costs/fees). 


Cash values are not guaranteed but policies maintain a minimum interest rate of accumulation. Universal policies also allow for partial cash value withdrawals which reduces the death benefit but provides immediate liquidity if/when needed. 

Indexed Universal Life (IUL)

Functions as a standard universal life policy with the key difference in that the cash value account credits interest to funds allocated to an indexed stock market strategy (such as the S&P 500 for example). Rate of returns in the cash value account fluctuate alongside the index market account's performance. 


An indexed universal life policy is a unique financial vehicle such as compared to an IRA, 401k or Money Market investment account; An IUL guarantees a minimum rate of return regardless of the index's performance. There is no risk for loss, accumulations are tax deferred and cash value withdrawals treated as a first in/last out basis (your principal is pulled first which is not subject to income tax, any growth/accumulation is)

Your Legacy - Your Benefits

Family Protection

Life Insurance Living Benefits

Life Insurance Living Benefits

Leverage a life insurance policy to supplement the family's principal wage earner's income to cover debts and final costs such as:

  • Funeral Expenses
  • Final medical expenses
  • Estate and other taxes
  • Probate costs
  • Consumer dept reduction/elimination
  • Estate Settlement Costs
  • Retiring a mortgage


Life Insurance Living Benefits

Life Insurance Living Benefits

Life Insurance Living Benefits

All forms of insurance (term, whole life, universal life) offer living benefits depending on the type of policy selected which include (but not limited to):

  • Tax Deferred Cash Value accumulation and growth.
  • Cash Value Loan collateral 
  • Accelerated death benefits in time of critical illness and/or disability
  • Life Insurance policy is a tangible estate building asset. 
  • Immediate cash liquidity on a first in, last out basis. 

Estate Building or Conserving

Life Insurance Living Benefits

Estate Building or Conserving

Life insurance policies create an immediate, secure and risk adverse estate that can be easily transferred to your beneficiary or to a trust so to mitigate estate taxes. 


Leverage a life insurance policy to preserve your existing assets and preserve your estate to be handed down to the next generation. 


Realize immediate liquidity upon benefit period. 

Retirement Planning

Business Owner Benefits

Estate Building or Conserving

Leverage life insurance cash value via withdrawals, cash surrender and/or policy loans at lower than market rates (compared to other financial vehicles 4-6%) as another vehicle to fund your retirement and supplement income during the golden years

Business Owner Benefits

Business Owner Benefits

Business Owner Benefits

Compliment your business' employee benefit offerings.


Premiums contributed on behalf of your employees are tax deductible.

Quality Planning

How Much is Enough?

Piedra Insurance Concepts is your trusted advisor to help right-size your policy based on your personal circumstances. We strive to allocate a policy that fits into your overall life plan and objectives. We structure polices based on at a minimum:

  • The composition of your family and the ages of the survivors
  • Your family’s education plans
  • Current debts and expenses
  • Lump-Sum cash needs and income replacement needs vs. existing liquid assets and/or other sources of income (social security, dividends, retirement accounts)
  • Likely future income requirements
  • Existence of other income, both spousal earned income and unearned income

Application Processing

Depending on risk factors and type of policy chosen, many policies and applicants do not require medical exams. However, for those that do, Piedra Insurance Concepts will guide you through the application and underwriting process every step of the way. 


Any and all physician exams, blood testing and/or urine testing is of no cost to you and can be utilized as part of your yearly health exam. 


PIC will review triggering risk factors that insurers look out for and identify the most feasible pathway forward. 

Start Planning Today

Helpful links to get you started!
Get Started!Tax bracket calculatorInterest Accumulation CalculatorSocial Security Benefit EstimatorS&P 500 Index Performance

Copyright © 2026 Piedra Insurance Concepts - All Rights Reserved.

Agnecy Licenses:

FL(resident): L137649

Powered by

This website uses cookies.

We use cookies to analyze website traffic and optimize your website experience. By accepting our use of cookies, your data will be aggregated with all other user data.

DeclineAccept